Mortgages Information Guide
Table of Contents
- What Is a Mortgage?
- Introduction to Mortgages
- Understanding Mortgages
- Types of Mortgages
- Applying for Mortgages
- Compare Mortgages Quotes
- Choosing the right Mortgage for you
- Benefits and Risks of Mortgages
- Tips for Managing Your Mortgage
- Compare Mortgages
- FAQ about Mortgages
What is a Mortgage?
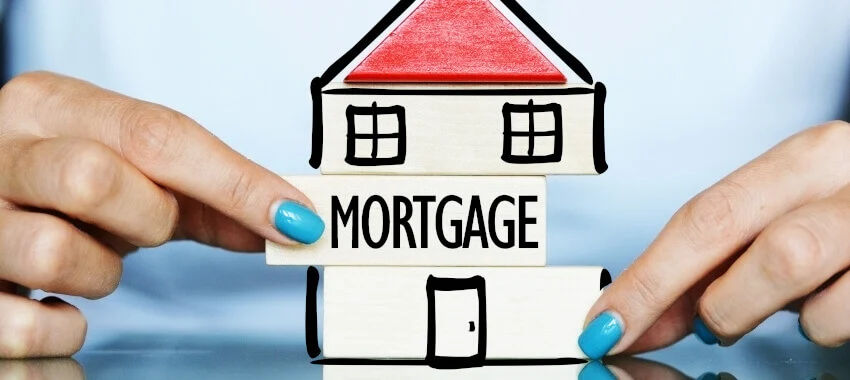
A mortgage is a secured loan typically used to finance the purchase of real estate. It is a legal agreement between a borrower and a lender, where the borrower pledges their property as collateral in exchange for receiving funds to purchase or refinance a home.
The borrower then repays the loan amount plus interest over an agreed-upon term, usually 15 to 30 years. Mortgages can have fixed or adjustable interest rates, with fixed rates remaining unchanged for the entire loan term while adjustable rates fluctuate based on market conditions.
Additionally, mortgage terms may include points, closing costs, and private mortgage insurance (PMI) depending on the lender’s requirements and the borrower’s financial situation. As such, obtaining a mortgage requires thorough research and understanding of one’s financial capabilities to ensure successful homeownership.
Compare Mortgages Quotes
Definition of a Mortgage
So, you’ve finally reached the point in your adulting journey where the word “mortgage” is floating around. But what exactly is it? Well, a mortgage is a fancy term for a loan that you take out to buy a home. It’s like borrowing a big chunk of change from a lender and promising to pay it back, along with interest. In simple terms, it’s a ticket to homeownership without having to fork out all the cash upfront.
Understanding the ins and outs of mortgages is crucial for anyone considering buying a home or property. This article will delve into the various types of mortgages available, the process of applying for a mortgage, factors that influence mortgage approval, and tips for managing your mortgage effectively.
Importance of Mortgages in Real Estate
Mortgages are the unsung heroes of the real estate world. Without them, most of us would be stuck in a forever-renting cycle. They make buying a home more manageable by spreading out the cost over several years. Thank you, mortgages!
Understanding Mortgages
If you’ve ever looked into mortgages, you’ve probably come across the term “mortgage rates.” These rates can have a significant impact on how much you pay for your home over time. In this section, we’ll break down what mortgage rates are all about.
Factors Affecting Mortgage Rates
Mortgage rates are influenced by a variety of factors, including economic conditions, inflation rates, loan terms, and your credit score. Before jumping into a mortgage, it’s essential to understand these factors to get a grasp of what rate you might qualify for.
Fixed vs. Variable Interest Rates
When it comes to mortgage rates, you’ll often have the choice between fixed and variable interest rates. Fixed rates stay the same throughout the life of the loan, providing stability. On the other hand, variable rates can fluctuate, potentially saving you money if rates drop but costing you more if they rise.
Understanding mortgages is crucial when navigating the complex world of real estate financing. Whether you’re a first-time homebuyer or looking to refinance, knowing the ins and outs of mortgages can help you make informed decisions.
Our Mortgages Guide delves into the various types of mortgages available, how to find the right lender, the application process, and tips for choosing the best mortgage that suits your financial needs and goals.
Types of Mortgages
Fixed-rate Mortgages
Imagine this: you lock in an interest rate that stays the same for the entire duration of your mortgage. No surprises, just good ol’ predictable payments. It’s like your mortgage buddy giving you a high-five and saying, “I gotchu, fam.”
Adjustable-rate Mortgages
On the flip side, adjustable-rate mortgages are a bit like playing mortgage roulette. Your interest rate can change after a certain period, which means your monthly payments can go up or down. It’s like riding a rollercoaster – exciting for some, nerve-wracking for others.
Government-insured Mortgages
These mortgages have a little extra something-something because they’re backed by the government. They offer benefits like lower down payment requirements and more lenient credit qualifications. It’s like having a cool uncle who co-signs your mortgage and vouches for you.
Finding the Right Mortgage Lender
Researching Mortgage Lenders
It’s like online dating but for mortgages. You want to swipe right on a lender who’s reliable, trustworthy, and won’t ghost you during the home buying process. Do your homework, read reviews, and ask around to find your perfect match.
Comparing Interest Rates and Terms
Just like shopping for the perfect pair of shoes, you’ll want to compare interest rates and loan terms from different lenders. Think of it as finding that sweet spot between a killer deal and a lender who won’t give you the runaround. It’s all about finding the mortgage that fits like a glove.
Applying for a Mortgage
Gathering Necessary Documents
Get ready to play detective because you’ll need to gather all sorts of paperwork – pay stubs, tax returns, bank statements, you name it. It’s like a scavenger hunt, but the prize at the end is your dream home.
Completing the Application Process
Once you’ve got all your documents in a neat little pile, it’s time to fill out that mortgage application. It’s like a job interview, but instead of selling yourself to a potential employer, you’re selling your creditworthiness to a lender. Show them why you’re the perfect match for that mortgage and get ready to embark on the homeownership adventure.
Best Mortgage Providers
If you’ve done the work and figured out that a personal loan makes sense for you, there’s no shortage of options to choose from. There are thousands of personal loan lenders out there, we break down a few of the best personal loans to choose from.
Compare Mortgages Quotes for Low Rates
Loan.co.uk

- Loan Amounts £1000 – £30,000
- Loan Terms from 3 to 18 months
- No Minimum Credit Score
About Loan.co.uk
An award winning, UK based loans and mortgages fintech, we have helped 1,000’s of people to consolidate their debt and fund home improvements, weddings and other life changing purchases. We have also helped 1000’s people to consolidate their over expensive debt. We are rated 4.97 out of 5 on Reviews.co.uk from more than 1650 reviewers.
Loan.co.uk provide completely free, no obligation quotes after searching our extensive panel of lenders with 1000’s of secured loans products from across the market using the most advanced technology in the country. Loan.co.uk is a credit broker not a lender. Loan.co.uk is authorised and regulated by the Financial Conduct Authority, FCA reg number 718486.
At Loan.co.uk, a senior leadership team with over a 100 years’ experience in digital loan acquisition and fulfilment, merges cutting edge proprietary technology, with a simple consumer brand and a team of the most helpful, experienced and professional employees in the country, on a mission to simplify the way UK consumers borrow money forever. We believe our fusion of hard working, talented people and forward-thinking technology can help you.
Compare Mortgages Quotes for Bad Credit
PostOffice.co.uk

- Loan Amounts £1,000 – £50,000
- Loan Terms 12 – 84 months
- APR Range 8.49% – 35.97%
- No Minimum Credit Score
About Post Office Secured Loans
At Post Office®, we aspire to be at the very heart of customers’ choice by becoming the most trusted provider of essential services to every person in the land.
We’re the UK’s largest retail network and the largest financial services chain in the UK with more branches than all of the UK’s banks and building societies put together. We also have growing direct channels such as contact centres and online – meaning we’re there for more customers, in more ways.
Post Office® and its partners offer over 170 products under four product pillars:
• Financial Services
• Mails & Retail (not currently available on the affiliate program)
• Government Services (not currently available on the affiliate program)
The Post Office® is now more than it ever was – an independent multi-channel business, with a vibrant, fast-growing financial services business, separated from Royal Mail and embarking on a new era of growth, modernisation and customer excellence in serving the UK population.
We have the largest retail network in the UK with almost 11,800 branches. And we want to grow further: we are a multi-channel business providing more than 170 products and services to our customers but our vision is to deliver more. Our financial services business, for instance, is one of the fastest growing in the UK, with almost 3 million customers, a growing mortgage business and a current account being piloted in 2013. The Post Office®, trusted and part of the fabric of our society, is an increasingly credible alternative to the high street banks.
Choose a loan between £1,000 and £25,000 with fixed monthly repayments.Post Office Money® Personal Loans are provided by Bank of Ireland (UK)
Compare Mortgages Quotes for Small Loans
AA Loans
- Loan Amounts £1,000 – £40,000
- Loan Terms 12 – 60 months
- APR Range 8.05% – 36.00%
- No Minimum Credit Score
About The AA Loans
AA Loans offer unsecured personal loans, they can be used for debt consolidation, car, home improvements etc. The rate is currently 3.3% (from 23rd June 2020) and is provided by Bank of Ireland UK.
USPs
- Fixed monthly repayments for the duration of the loan
- Spread the repayments over 1-7 years
- No arrangement or set up fee
- Other Loan amounts and terms available. Loan amounts range from £1,000 to £25,000, with terms available from 1-7 years.
To apply for an AA Loan applicants must:
- Have been a UK resident for at least 3 years
- Be over 21 and no older than 70 when the loan term ends
- Have a regular (minimum) annual income of £12,000 (gross). If you are self- employed you must have been employed for a minimum of 2 years
- Have a UK based bank or building society current account that can pay direct debits
- Ensure that they can meet the repayments, as missed payments incur a charge and could have severe consequences on their ability to obtain future credit
Compare Mortgages Quotes for Fast Funding
MasterLoan.co.uk

- Loan Amounts £2,000 – £36,500
- Loan Terms 12 – 72 months
- APR Range 7.99% – 35.99%
- No Minimum Credit Score
About MasterLoan.co.uk
Masterloan.co.uk compare 100’s of different loan plans, no matter where you are in the UK. Our dedicated home loans team will search and find the best solution for you and at all times we will keep you informed of you home loan application. We offer homeowners and business owners loans and mortgages and offer loans from £1,000 up to £2.5 Million with fast market leading completions.
Compare Mortgages Quotes for No Fees
ComparetheMarket.com

- Loan Amounts £5,000 – £100,000
- Loan Terms 12 – 84 months
- APR Range 8.99% – 23.43%
- No Minimum Credit Score
About ComparetheMarket.com
ComparetheMarket.com is a leading online platform that offers a wide range of financial products and services. With a mission to empower individuals with the knowledge and tools to make informed financial decisions, comparethemarket.com has become a go-to destination for those seeking various insurance products, financial services, and more.
Choosing the Best Mortgage for You
The things that make homeownership dreams a reality, but also make our heads spin with confusion. Fear not, dear reader, for we’re here to guide you through the maze of mortgage options to help you find the one that’s just right for you.
Factors to Consider in Mortgage Selection
When it comes to choosing a mortgage, there are a few key factors to keep in mind. First up, consider your financial situation. How much can you afford to put down as a down payment? What’s your credit score like? These factors will play a big role in determining the type of mortgage you can qualify for.
Next, think about the type of mortgage that suits your needs. Are you looking for stability with a fixed-rate mortgage, or are you willing to take a gamble with an adjustable-rate mortgage? Each option has its pros and cons, so weigh them carefully.
Don’t forget to factor in additional costs like closing fees, insurance, and taxes. These can add up quickly and impact your overall budget, so it’s crucial to account for them when choosing a mortgage.
Seeking Professional Advice
Navigating the world of mortgages can be overwhelming, to say the least. That’s where mortgage professionals come in. Mortgage brokers and financial advisors can provide valuable insight and guidance to help you make an informed decision.
Don’t be afraid to ask questions and seek clarification on anything you’re unsure about. A professional’s expertise can help you navigate the complexities of mortgages with confidence, ensuring you make the best choice for your financial future.
Mortgage Repayment Options
Paying off a mortgage is a long-term commitment, and understanding the repayment options available to you can make a big difference in managing your finances. Let’s dive into the different ways you can repay your mortgage.
Amortization Schedules
Amortization schedules outline how your mortgage payments are structured over time. They show the breakdown of how much of each payment goes towards the principal loan amount and how much goes towards interest. Understanding these schedules can help you plan your finances better.
Refinancing Options
Refinancing your mortgage involves replacing your current loan with a new one that has more favorable terms. This could mean lower interest rates, changing from an adjustable-rate to a fixed-rate mortgage, or even tapping into your home’s equity. It’s essential to weigh the pros and cons before deciding to refinance.
Benefits and Risks of Mortgages
Owning a home through a mortgage comes with its share of benefits and risks. Let’s explore what they are so you can make informed decisions when diving into homeownership.
Benefits of Homeownership through Mortgages
Owning a home can provide stability, build equity, and offer tax benefits. Mortgages allow individuals and families to achieve the dream of homeownership, which can lead to a sense of pride and belonging in a community.
Risks of Defaulting on a Mortgage
Defaulting on a mortgage can have serious consequences, including foreclosure and damage to your credit score. It’s crucial to make timely payments and understand the terms of your mortgage to avoid falling into financial hardship.
Tips for Managing Your Mortgage
Managing your mortgage is key to ensuring your financial well-being. Here are some practical tips to help you stay on top of your mortgage payments and navigate any challenges that come your way.
Creating a Budget for Mortgage Payments
Setting up a budget specifically for your mortgage payments can help you track your expenses and ensure you make timely payments. Be realistic about what you can afford and prioritize your mortgage payments to avoid financial strain.
Emergency Savings for Mortgage Challenges
Having an emergency fund can provide a safety net in case unexpected financial challenges arise, such as job loss or medical emergencies. Aim to have enough savings to cover several months’ worth of mortgage payments to give yourself peace of mind and financial security
.In conclusion, mortgages play a pivotal role in the real estate market, enabling individuals to achieve their dreams of homeownership. By familiarizing oneself with the different types of mortgages, understanding the application process, and being aware of factors affecting mortgage approval, individuals can make informed decisions when entering into a mortgage agreement. Remember, managing your mortgage responsibly can lead to long-term financial stability and the satisfaction of owning a place to call home.